Northern Virginia Home Buying FAQs: Clear Answers for Buyers
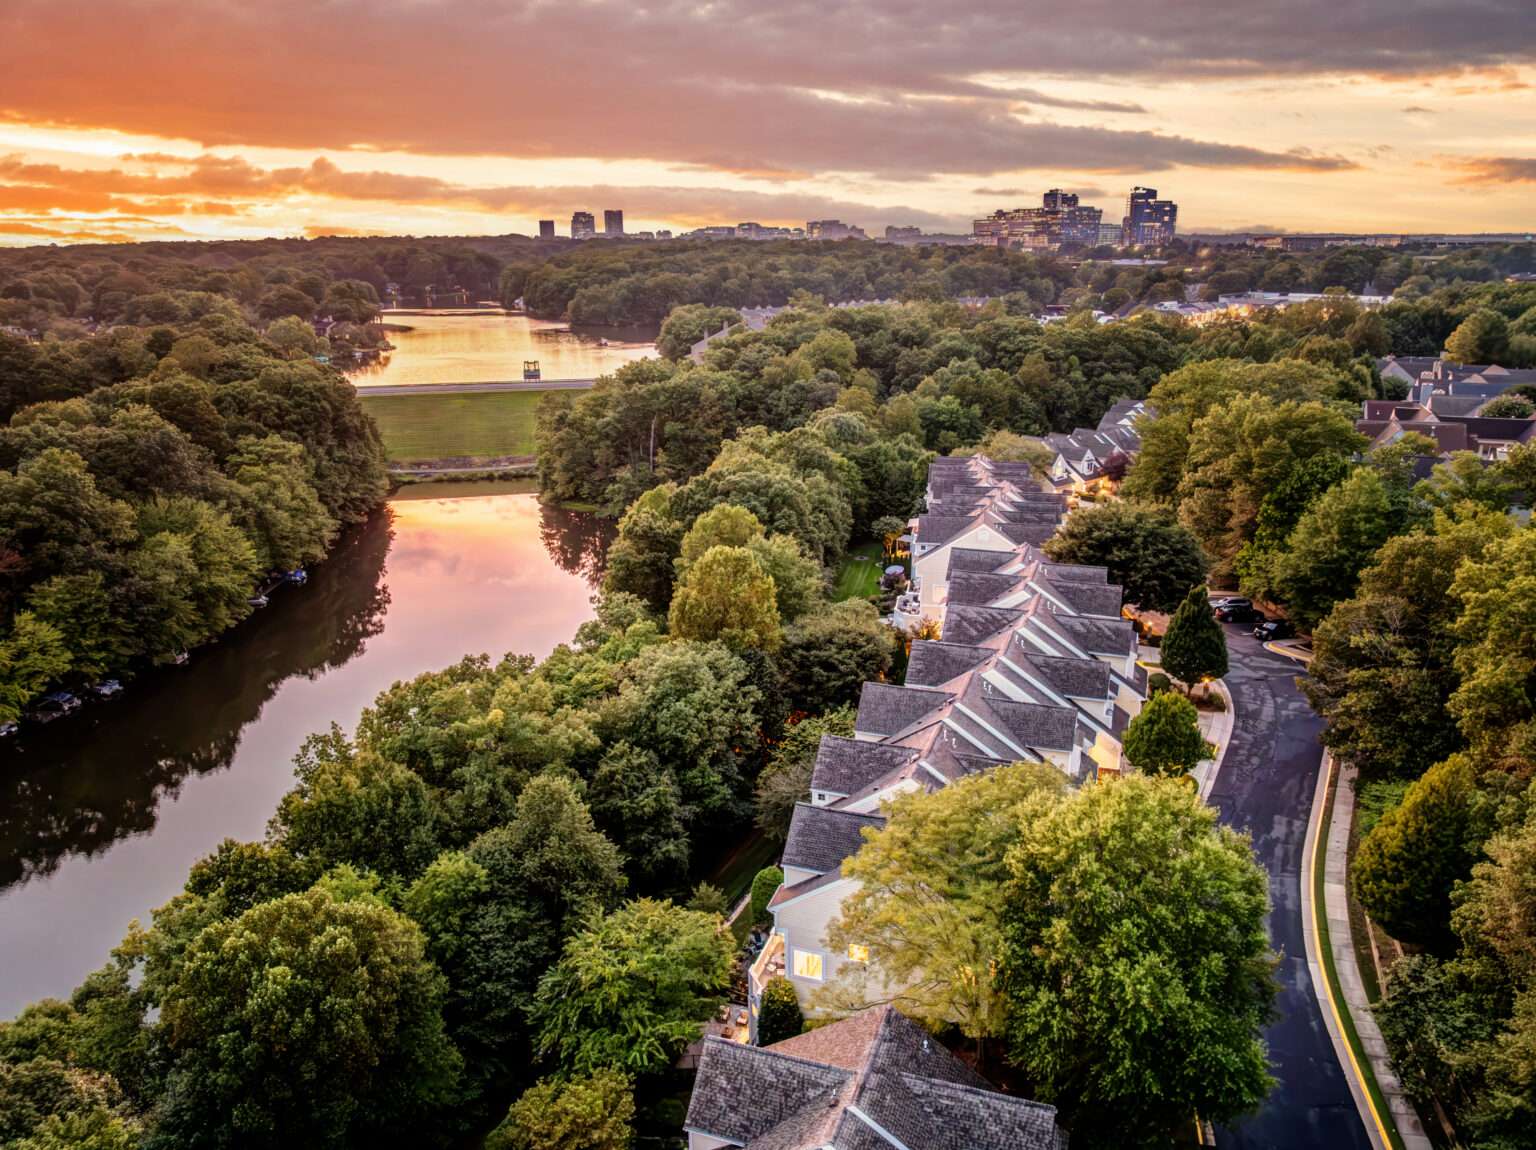
Buying a home in Reston, Fairfax, Arlington, Loudoun County or elsewhere in Northern Virginia comes with questions that deserve clear answers. Here’s what to know about getting started, planning your cash, making an offer, reviewing association documents and getting to closing.
Start with the question that matters most to you: Getting started • Costs • Offers and inspections • HOAs and condos • Closing
Getting Started and Getting Preapproved
What should I do first if I want to buy a home in Northern Virginia?
Start with a monthly payment you can comfortably manage, not just a listing price. Then talk with a lender about your borrowing options and decide which locations, property types and commute needs matter most. A clear budget and a short list of priorities make your home search more focused from day one.
For the full sequence, see the step-by-step home buying guide.
Do I need mortgage preapproval before touring homes?
There’s no universal legal requirement to get preapproved before viewing a house, but preapproval helps you shop within a realistic borrowing range and prepare for an offer. A lender reviews your financial information and may issue a letter stating how much you could qualify to borrow. That letter is not a final loan approval, and your own comfortable budget may be lower.
Do I need a buyer’s agent, and what will I sign?
You can choose whether to work with a buyer’s agent. If you do, expect to discuss what the agent will do, how long the relationship lasts and how compensation works before signing a representation agreement. Fees and who ultimately pays them are negotiable; don’t assume the seller automatically covers them. Ask for an explanation of any exclusivity, termination and payment terms before agreeing.
Virginia also has rules on how brokerage relationships must be disclosed. See the state law. If you’re buying your first home, Nikki’s first-time buyer resource offers a more detailed starting point.
Budget, Mortgage and Upfront Costs
How much cash do I need to buy a home?
Plan for more than a down payment. You may need money for an earnest-money deposit when your offer is accepted, closing costs and prepaid expenses at settlement, plus moving costs and a cash cushion afterward. The amount depends on the loan, the home, the contract terms and other circumstances. Your lender’s estimate is more useful than a blanket percentage.
What’s the difference between earnest money, a down payment and closing costs?
These are three different parts of your purchase budget. The earnest-money deposit is generally applied toward the amount you owe at settlement if the sale closes, so don’t automatically count it as an extra expense on top of your total cash to close.
| Expense | What it means | When it matters |
|---|---|---|
| Down payment | The portion of the purchase price you pay rather than finance. | Usually part of the cash required at closing. |
| Earnest-money deposit | Money held under the contract to show commitment after an offer is accepted. | Often paid earlier and credited toward your closing funds if the transaction closes. |
| Closing costs and prepaids | Lender, title and other settlement charges, plus items such as prepaid taxes or insurance. | Reviewed in the lender’s estimates and final closing documents. |
Are there low-down-payment loans or homebuyer assistance programs?
Possibly. Options may include conventional, FHA and VA loans, along with assistance programs for eligible buyers. The right program depends on your qualifications, loan rules, occupancy, income and other requirements. A lender can walk you through the tradeoffs instead of simply pointing you to the smallest down payment.
For an official state starting point, review the Virginia Housing Down Payment Assistance Grant. Check eligibility and availability before you count on assistance in your budget.
What affects my actual monthly mortgage payment?
The loan amount, interest rate and repayment term are only part of it. Your monthly housing costs can also include property taxes, homeowners insurance, mortgage insurance where required, and HOA or condo dues. Ask your lender for a complete estimate and account for expenses you’ll pay outside the mortgage bill.
You can explore the numbers with Nikki’s mortgage payment calculator, but rely on your lender’s figures when making decisions.
Offers, Inspections and Contract Protections
What makes a competitive offer besides the price?
A seller may also care about how you’ll finance the purchase, your proposed closing date, any concessions you request and your contract conditions. A higher price with uncertain financing or unrealistic deadlines may not be as appealing as it looks. Think through each term based on the specific property and what you can realistically follow through on.
For a broader planning reference, use the buyer handbook.
Do I have to waive the home inspection to win a house?
No. There is no blanket requirement to waive an inspection. An inspection helps you understand the condition of a home; an inspection contingency is a separate contract protection that may give you defined options if problems are found. Waiving that protection can leave you with fewer ways to respond after signing. Understand the exact wording and deadlines before you change or give up an inspection right.
Virginia’s residential property disclosure notice specifically stresses buyer due diligence, including the option of getting an inspection.
Can I get my earnest-money deposit back if the sale falls through?
Sometimes, but not simply because you change your mind. Whether the deposit must be returned depends on the contract, any applicable contingency, how the transaction ends and whether required notices are given on time. Before signing, make sure you understand the situations that could put the deposit at risk. If a dispute arises, have the contract reviewed by a qualified Virginia real estate attorney.
The National Association of REALTORS® explains common contract contingencies and why their terms matter.
What happens if the appraisal comes in below my offer?
The lender may not be willing to finance the full price you offered. Depending on the loan and contract, possible next steps include asking the seller to adjust the price, bringing additional funds or using rights under an applicable appraisal or financing contingency. Don’t assume an appraisal shortfall automatically lets you cancel without consequence; check the signed agreement and deadlines.
HOAs, Condos and Local Property Due Diligence
What should I check before buying a Reston townhouse or Northern Virginia condo?
Look beyond the advertised monthly fee. Association rules and financial obligations can affect what you pay, what you can change and how you use the property. In Reston and other parts of Northern Virginia, review the specific home’s association documents rather than assuming every community has the same requirements.
Regular dues and what they actually cover.
Reserves, current or planned special assessments, and major projects.
Governing documents, restrictions and any rental or renovation rules.
Who repairs roofs, exterior features, shared systems and common areas.
Parking, storage, amenities and any additional association obligations.
For local background, see the Reston Association neighborhood guide.
Can I cancel after receiving an HOA or condo resale certificate in Virginia?
Virginia law provides certain cancellation rights tied to delivery of the resale certificate, but the deadline depends on the contract and when the documents arrive. Under the Resale Disclosure Act, if the parties did not agree to a different cancellation period, the statute generally provides a three-day default measured from ratification or receipt, depending on delivery timing. If the certificate has not been delivered, different rules can apply. Written notice must follow the contract’s requirements. To confirm your deadline right away, ask your agent—and, for a specific cancellation question, a Virginia real estate attorney.
Read the precise requirements in Virginia Code § 55.1-2312.
Does Virginia’s seller disclosure replace a home inspection?
No. Virginia’s residential property disclosure framework places significant responsibility on buyers to investigate a property. The required notice does not promise that the home is free of defects. Other separate disclosures can still apply, so don’t treat the general notice as permission to skip all document review. Decide what inspections, records and professional advice you need before the contract’s deadlines expire.
The current Virginia DPOR disclosure statement describes the buyer due-diligence notice.
Timeline and Closing
How long does buying a home and getting to closing take?
There is no single timetable. Finding the right property might take days or months; the period after an accepted offer depends on the agreed settlement date, financing, appraisal, title work and any contract conditions. If you are coordinating a lease ending, a job move or a military relocation, discuss the dates before making an offer—not after the moving truck is booked.
What should I check before closing day?
Review the final numbers and paperwork early enough to ask questions. For most covered mortgages, the lender must provide a Closing Disclosure at least three business days before closing. Compare it with your most recent Loan Estimate, especially the loan terms, cash to close and charges that changed.
Compare the Closing Disclosure with your latest Loan Estimate and flag any differences.
Call your settlement company using an independently verified number before sending any funds; do not trust last-minute emailed changes to wire instructions.
Arrange the final walkthrough and check the property’s agreed condition.
Review title, deed, loan and settlement documents and confirm what identification or funds you must bring.
Use the Consumer Financial Protection Bureau’s closing-document checklist for a closer look at what to review.
Have a Northern Virginia Home Buying Question?
If you are weighing a particular home, trying to understand an offer term or deciding where to start, ask Nikki Lagouros about the question in front of you. You don’t need to have every detail figured out first.
Contact Nikki to discuss your Northern Virginia home search.
This guide provides general information, not legal, mortgage or individualized financial advice. Your contract, lender documents and current Virginia law control the details of your transaction.